Stablecoin Savings Fade When African Payments Reach the Off-Ramp
Three large African payment providers found that stablecoin settlement was fast, but costly local-currency conversions could erase expected savings in thin markets.
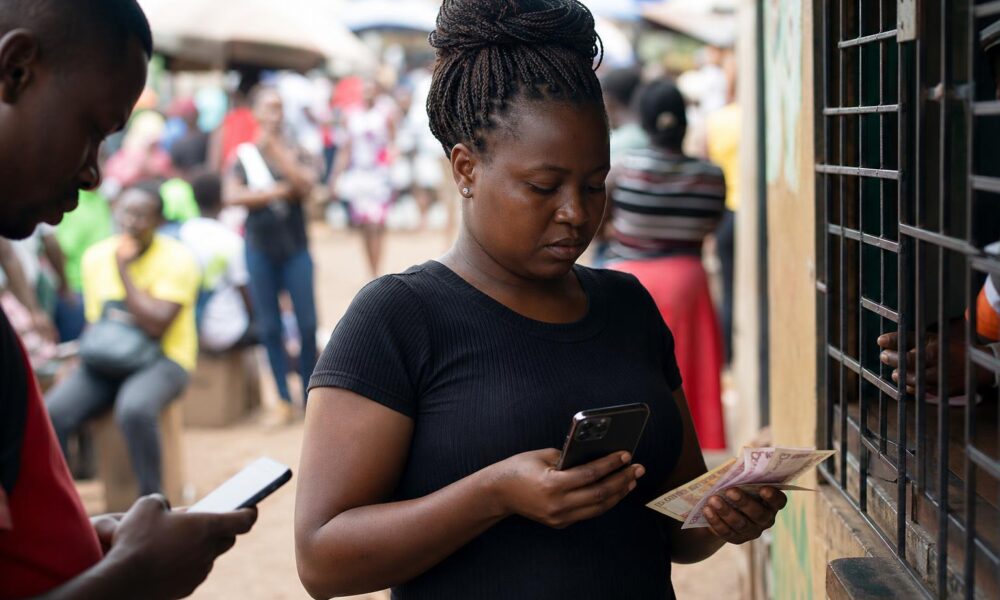
Three of Africa’s largest multi-licensed payment service providers have found that stablecoins can speed up cross-border settlement without necessarily making payments cheaper once funds must be converted into local currency.
Table Of Content
The providers independently tested stablecoin payment rails over the past three years for transactions involving merchants, e-commerce platforms, remittance companies and trade settlements. Although the models initially promised to reduce cross-border money-movement costs by ten times, the pilots showed that local-currency off-ramps remained a significant constraint.
Conversion costs undermine savings
According to the report, converting stablecoins back into local currency could cost more than 8%. In markets with limited liquidity, foreign-exchange costs, price slippage, payout fees and local payment-rail charges were enough to remove much of the expected benefit.
“The blockchain worked, but the off-ramp did not,” Gwera Kiwana said. Kiwana is Partnerships Lead at Morse, serves on the investment committee of Launch Africa Ventures and has angel-invested in more than a dozen Africa-focused startups, according to the report.
The report cited figures from the World Bank showing that sending $200 from Sub-Saharan Africa costs an average of 8.5%, compared with 6% globally. It also cited Chainalysis as estimating that stablecoins could reduce the cost of a $200 remittance from the region by about 60%.
However, Kiwana said payment companies should compare stablecoin pricing with the cheapest option already available to customers, rather than only with regional remittance averages. The report cited World Bank figures putting the cost of digital-only money-transfer services at 3.54% globally and payouts into mobile wallets at 3.92%.
Fast settlement does not guarantee local access
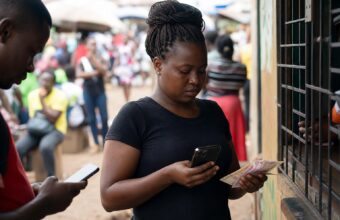
Stablecoins such as USDC and USDT can provide final blockchain settlement within seconds. But that settlement does not automatically create access to spendable local currency or local payment networks.
“The blockchain gives you finality. It does not give you naira or shillings,” Kiwana said.
The report said the providers also examined conditions in the CFA region, where spread, slippage and payout fees together exceeded 8% for typical transfers of $100,000. In some cases, cross-border rails cost ten times as much as a local payment when transaction volumes were below the level needed to support local infrastructure.
These pressures were particularly important in thin markets, where there may be too few licensed liquidity providers or local-currency counterparties to support competitive pricing.
Compliance narrows the liquidity pool
Licensed payment companies must also balance regulatory controls with access to market liquidity. The report said major liquidity providers generally work only with businesses that have completed business-verification checks. Some counterparties available in open or informal marketplaces may not meet those requirements.
“So the stricter your compliance, the shallower the market you can legally touch,” Kiwana said.
She described some liquidity markets as negotiations conducted through messaging services and telephone calls rather than as deep, transparent marketplaces. “That is not a market. It is a negotiation,” she said.
Providers adopt a mixed model
After testing the off-ramps, the three payment providers adopted combinations of stablecoin and traditional bank rails. Stablecoins were used where local liquidity was sufficiently deep, while bank-based systems remained necessary in corridors where it was not.
Kiwana said stablecoins still have a role in business treasury, dollar savings and corridors with deep, licensed liquidity. The report also said Chainalysis found that Sub-Saharan Africa led the world in crypto growth through June 2026.
For companies assessing a new corridor, the report recommends pricing stablecoin conversions at the actual transaction size and under the worst conditions of the week. It also advises firms to count the licensed counterparties they can use, model the impact of losing a major liquidity venue and compare the result with the cheapest existing payment option.
“Where a stablecoin corridor cannot beat traditional rails, do not force it,” Kiwana said. She added that future progress would depend less on faster blockchain networks than on deeper, licensed local liquidity.
No Comment! Be the first one.