OPay, Moniepoint Show Different Paths to Growth in Nigeria’s Fintech Market
OPay and Moniepoint reported sharply different transaction profiles and lending activities in 2025, as new Central Bank of Nigeria market-structure rules add another consideration for their expansion.
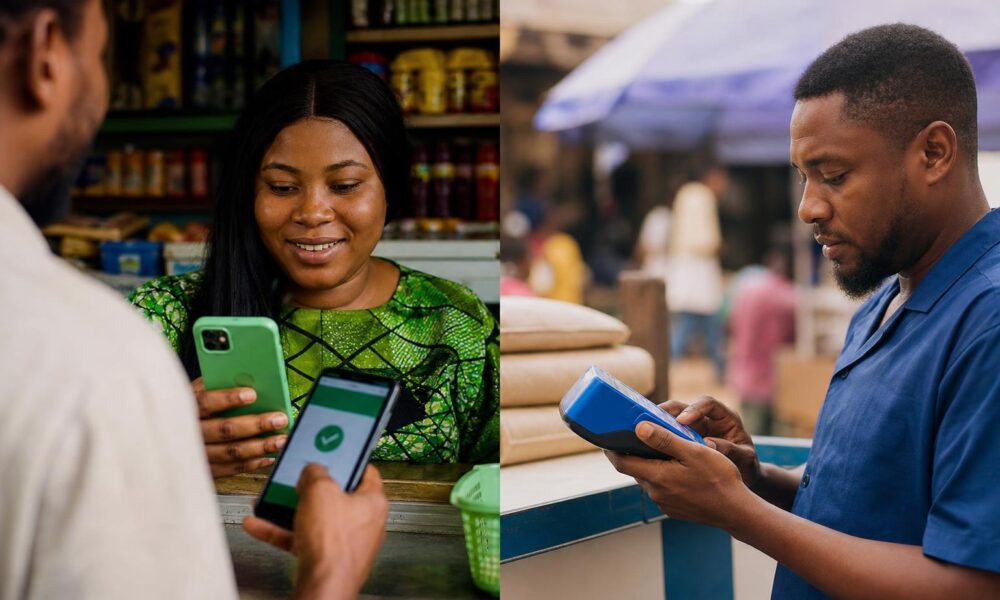
OPay and Moniepoint are pursuing different routes to growth in Nigeria’s payments market, according to a comparison of their 2025 transaction volumes, revenue, lending activity and credit exposure.
Table Of Content
Nigeria processed more than ₦1.2 quadrillion ($880.51 billion) in electronic transactions during 2025. Together, the two fintech companies reported processing $644.85 billion of that value.
OPay handled more transactions
Moniepoint said it processed 14 billion transactions worth ₦412 trillion, equivalent to $286.85 billion, in 2025. OPay reported 62.3 billion transactions valued at $358 billion.
Based on those disclosures, OPay handled 4.45 times as many transactions as Moniepoint. Moniepoint, however, had the higher average transaction value, at approximately $20.49 compared with OPay’s $5.75.
The difference reflects the companies’ reported operating profiles, although the available figures do not establish exactly what drives it. OPay has a consumer-payments focus, while Moniepoint has a stronger merchant-processing orientation.
Moniepoint said it serves more than 20 million businesses and individuals. OPay reported 50.1 million monthly active users and said its digital wallets were used an average of 209 times per user each month. Moniepoint reported that its cards were used 1.7 million times daily.
OPay operates in Indonesia, Egypt and Pakistan, although Nigeria generated 88.1% of its revenue in 2025. Moniepoint operates largely in Nigeria and has recently expanded into Kenya. Both companies hold microfinance banking licences.
Different approaches to lending
OPay disclosed $536.25 million in revenue for 2025. Moniepoint does not publicly disclose its revenue or profit figures, making a direct financial comparison difficult.
OPay originated $938.3 million in new loans in Nigeria during 2025, an increase of 284.71% in one year. Its quarterly unique borrowers in the country rose to 4.6 million from 2.1 million a year earlier.
Loan financing generated $260.3 million for OPay in 2025, representing 48.5% of its total revenue and an increase from $71.5 million in 2024. The company has also introduced merchant lending and is looking to expand it. OPay said these loans generally have higher limits, lower rates and longer repayment periods aligned with business cash-flow cycles.
Moniepoint said it disbursed more than ₦1 trillion, or $696.23 million, in loans to small businesses in 2025. It also reported that businesses receiving its loans recorded an average 36% increase in transaction value after accessing credit. The company uses merchant relationships and transaction data to support business-credit decisions.
An illustrative calculation in the comparison found that if Moniepoint generated revenue at OPay’s 0.15% revenue-to-transaction-value rate, it would produce approximately $430.28 million. That is not an estimate of Moniepoint’s actual revenue, as the companies may differ in transaction mix, fees and other revenue sources.
Credit risk and regulation
OPay’s growing lending activity has been accompanied by a higher expected-credit-loss provision. The provision increased from $24.8 million in 2024 to $121.3 million in 2025, equivalent to approximately 46.6% of its loan-financing revenue. Expected-credit-loss provisions indicate credit-risk exposure but are not the same as realised loan losses.
OPay reported income before taxes of $110.79 million in 2025, equal to approximately 20.66% of its disclosed revenue. Any comparison with Moniepoint based on OPay’s revenue yield or margin would be illustrative rather than a reported Moniepoint result.
The Central Bank of Nigeria reported that non-performing loans rose to 7% in 2025. The available information does not provide a specific Moniepoint non-performing-loan figure.
Regulatory requirements introduced by the CBN in June 2026 could also affect the companies’ expansion strategies. Under the market-structure rule described in the comparison, a licensed financial institution controlling more than 25% of the consumer-issuing market would be limited to a maximum 15% share of merchant-acquiring activities.
The requirements create an additional consideration for fintech companies operating across consumer payments, merchant services and lending as they seek to scale.
No Comment! Be the first one.